Is your financial plan ready? When we think about cancer, our first thoughts are understandably about health: treatment, doctors, recovery and getting better.What we may think about less is everything else that continues around a diagnosis.
The bond or rent still needs to be paid. Groceries still need to be bought. Children still need to get to school. Family responsibilities continue. And depending on someones circumstances, recovery may also bring additional costs or changes to their ability to work.It raises an important question: if a serious illness changed your life, how prepared would you be for its financial impact?
Why this conversation matters now?
If youre living with cancer, have been through treatment, or are supporting someone who has, youll know how quickly life can change.
And for those of us who are healthy, serious illness can still feel distant, something well think about when were older or if our circumstances change.But claims experience shows why the conversation is relevant now.
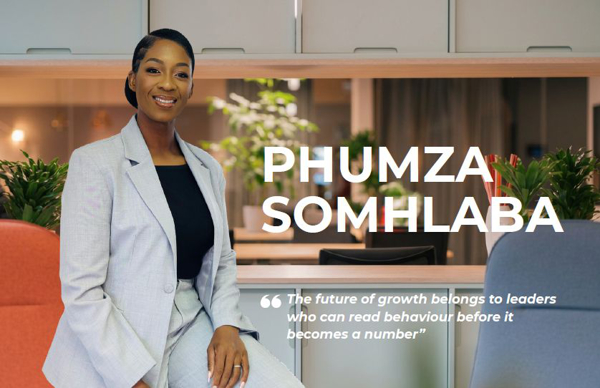
In 2025, Old Mutual paid R827 million in Severe Illness benefits, with 68% of Severe Illness claims relating to cancer, coronary artery bypass grafts, heart attacks and strokes. For Phumza Somhlaba, Marketing Manager at Old Mutual Personal Finance, planning for serious illness isnt about expecting the worst.
“Financial planning isnt about living in fear of what might happen. Its about understanding how the life youve built could be affected if something unexpected happened, and knowing what you already have in place to help protect it.”
“I have medical aid, so Im covered.
”Having medical aid is an important part of preparing for healthcare needs. But medical treatment and the broader financial impact of a serious illness are not the same thing.
A diagnosis may bring costs and financial pressures beyond treatment itself, from travel and additional support during recovery to everyday household commitments that continue regardless.
And everyones circumstances are different. “Medical aid plays an important role in helping with healthcare costs, but that shouldnt be the end of the financial conversation. Ask yourself what would happen to the rest of your financial life during recovery, your everyday commitments, your savings, your responsibilities and the people who depend on you,” says Somhlaba.
This distinction matters in a country where financial protection against serious illness remains limited. The 2025 ASISA insurance gap study estimates that more than 85% of South African earners have no severe illness cover. (Association for Savings and Investment South Africa (ASISA), 2025 Insurance Gap Study).
Five questions worth asking before you need the answersYou dont need to understand insurance terminology to start thinking about your financial preparedness.
Ask yourself:
What financial commitments would continue if I became seriously ill?
What costs might arise that my medical aid may not cover?
How long could I comfortably rely on my savings?
Who else would be financially affected?
And do I understand what my existing financial protection actually covers?
If youre unsure about some of those answers, thats a conversation worth having.
Severe Illness Cover is one option that can provide financial support following a qualifying claim, giving you financial flexibility when a serious illness affects more than your health.
Old Mutual Protect Severe Illness Cover includes cover for conditions such as cancer, heart attack and stroke, subject to applicable terms, underwriting and claim criteria.“You dont need to have all the answers before speaking to a financial adviser. Start with your life, your responsibilities and the questions youre unsure about.
Change happens with the right conversation,” says Somhlaba.
Start the conversation before you need itUnderstand the financial protection you already have and whether there may be gaps worth considering.Start the conversation with a financial adviser.