By Mzukona Mantshontsho
On Thursday, November 19, 2026, the South African Reserve Bank’s Monetary Policy Committee will announce its last interest rate decision of 2026.
The committee has raised the repo rate twice this year, in May and September, taking it to 7.25% and the prime lending rate to 10.75%.
Economists are split on whether the committee will raise or hold the interest rate. Statistics South Africa will also release consumer inflation on Wednesday, November 18, which could impact the committee’s interest rate decision.
According to Debt Busters’ third-quarter report, debt counselling applicants taking home over R50,000 in South Africa spend roughly 97% of that pay on debt repayments.
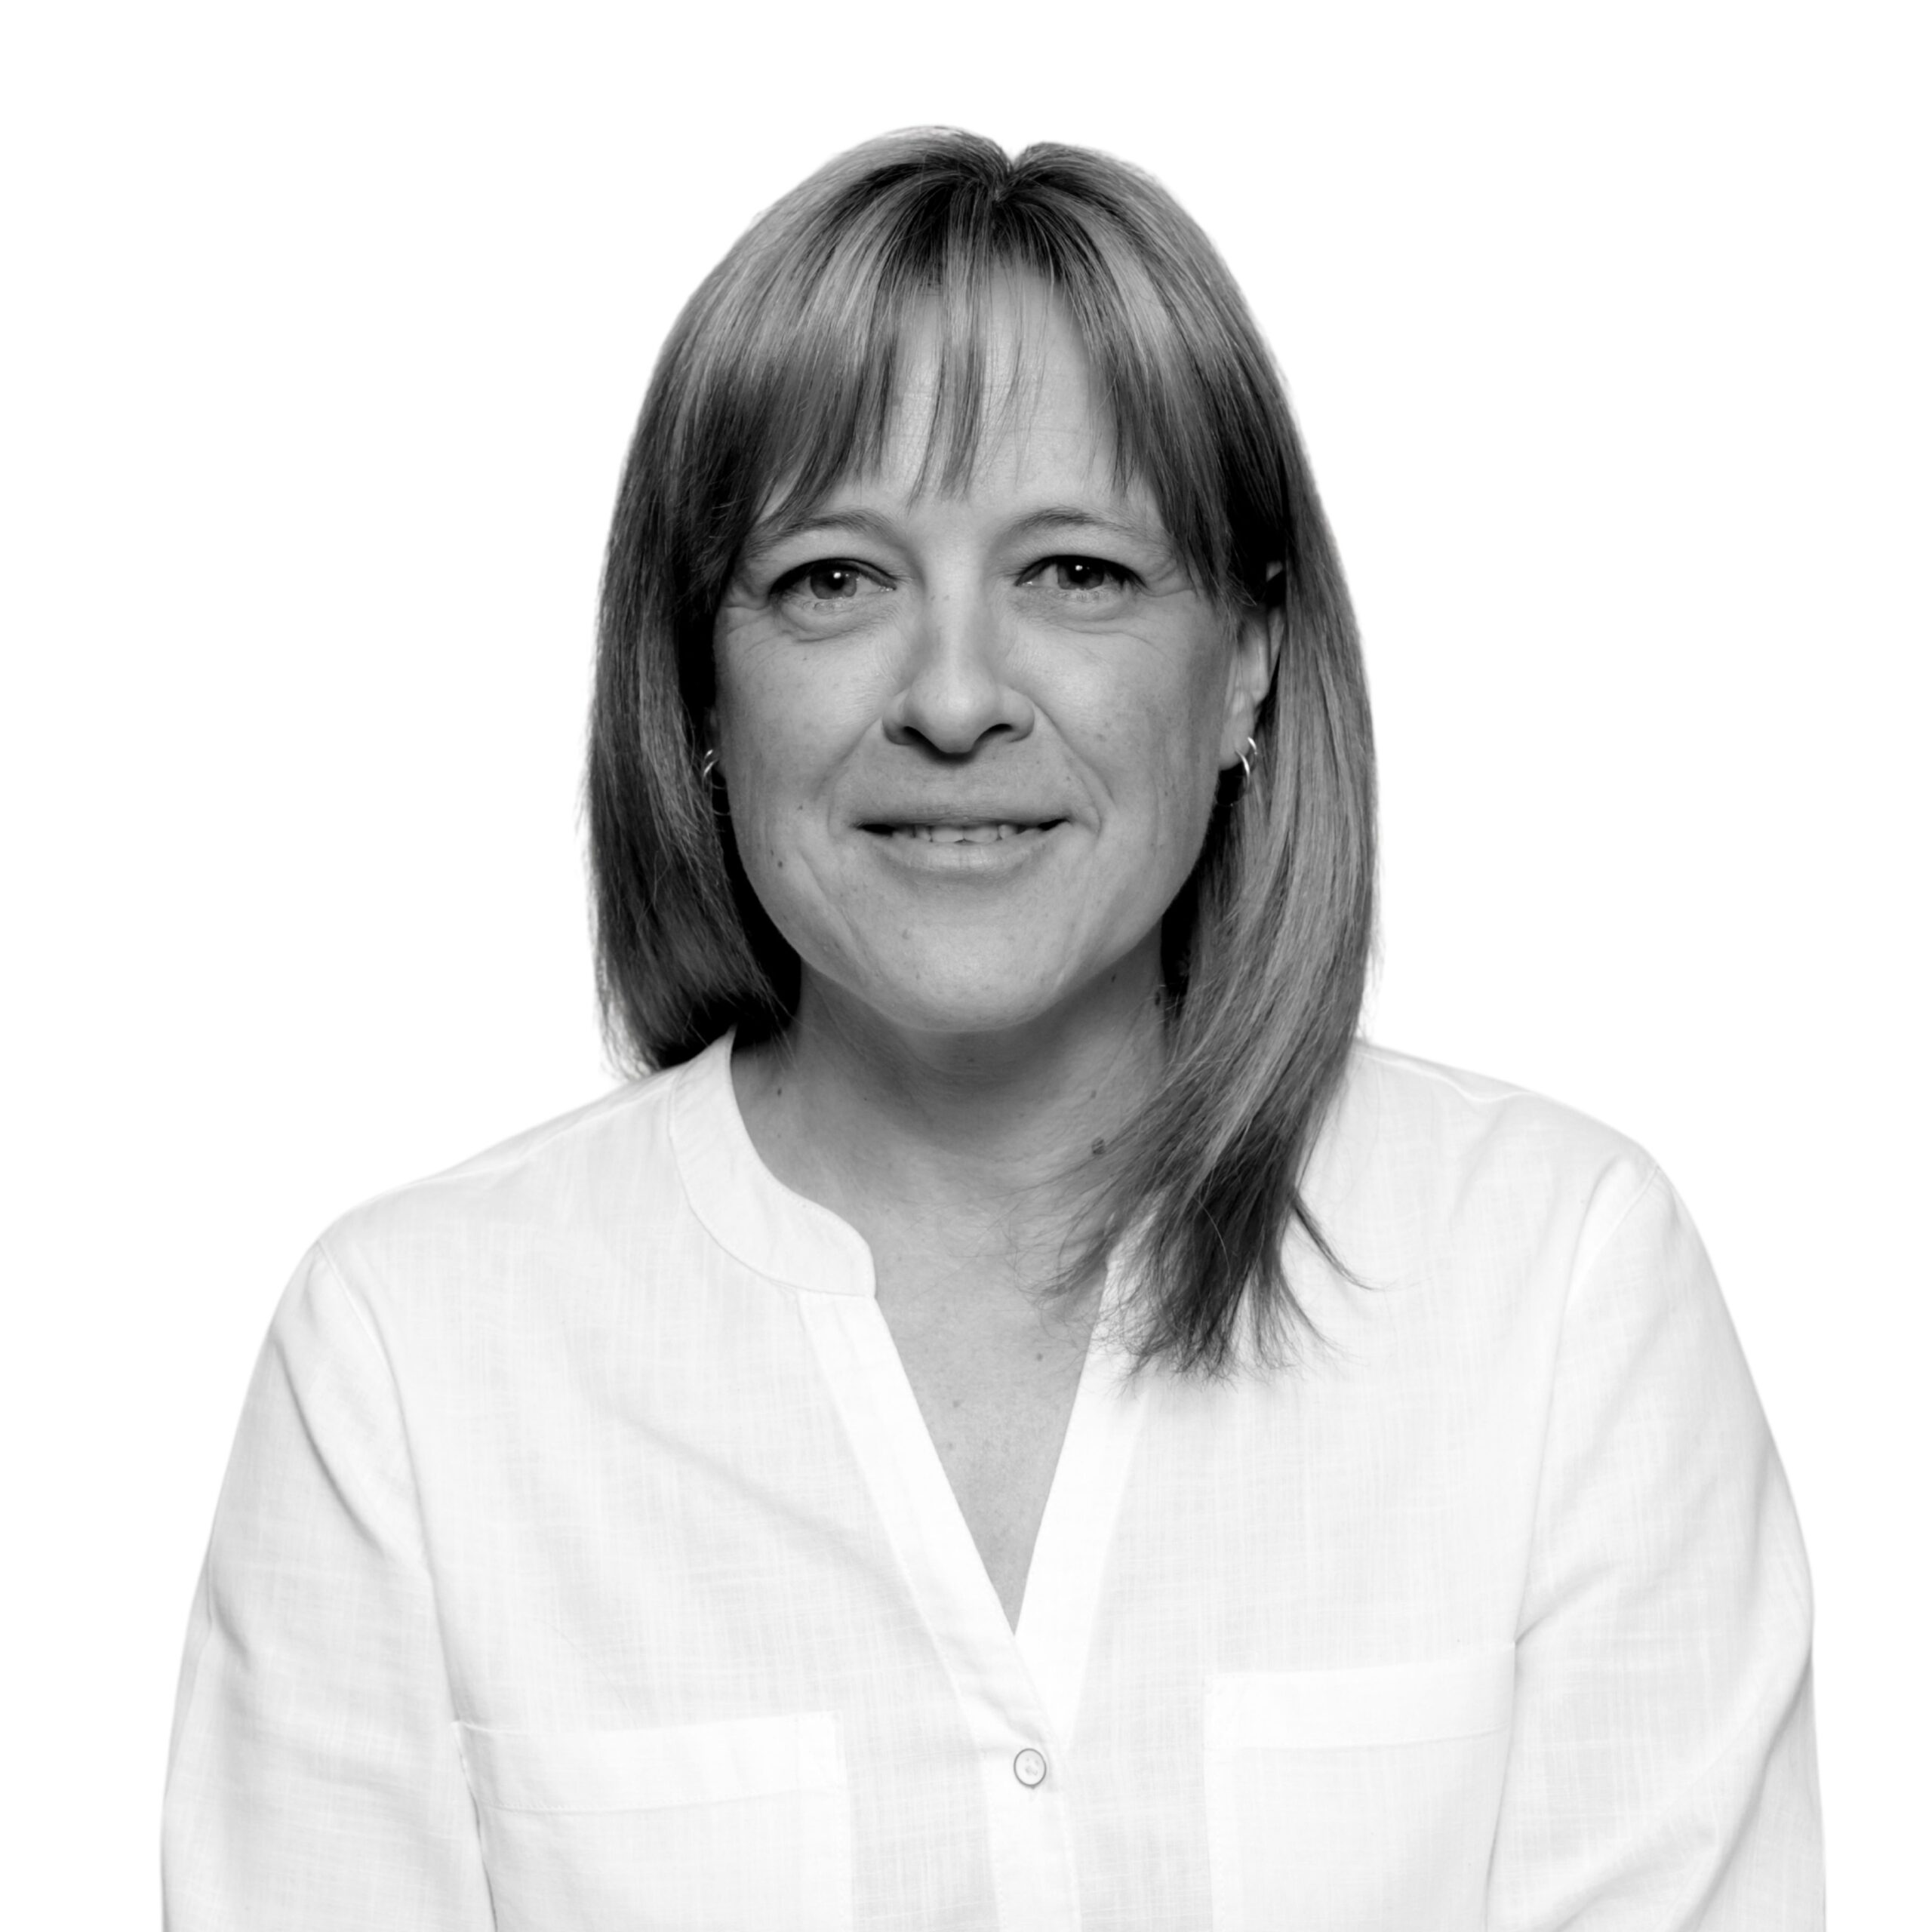
Spoke to Annaline van der Poel, the Chief Customer Experience Officer at Debt Rescue, one of South Africa’s leading debt counselling companies. She has an excellent understanding of the regulatory frameworks underpinning the lending and credit environment, as well as debt restructuring, policy development and dispute resolution.
Through Debt Rescue’s daily work with over-indebted consumers, she has first-hand insight into how interest rate movements and borrowing costs affect household budgets, credit affordability and the ability to keep up with debt repayments. Van der Poel has a particular interest in helping consumers manage their finances and understand the impact of changes in the global and local financial landscape on their personal finances.
Van der Poel holds a Bachelor of Laws (LLB) from Unisa and is a Registered Debt Counsellor with the National Credit Regulator. She is a frequent commentator on consumer credit matters and is regularly invited to share insights on household debt and financial wellbeing in radio and television interviews.
“We at Debt Rescue expect the South African Reserve Bank to leave the repo rate unchanged at 7.25% on Thursday, although another 25-basis-point increase remains possible,” Annaline van der Poel.
“While inflationary pressures continue to concern policymakers, we believe there is merit in allowing September’s increase more time to influence the economy. Wednesday’s inflation figures will provide additional insight into the direction of consumer prices.
“For households, the implications extend well beyond the announcement itself. With prime currently at 10.75%, borrowing is already expensive. A further increase would raise repayments on variable-rate home loans and vehicle finance, leaving indebted consumers with even less disposable income.
“Importantly, consumers should recognise that credit cards, personal loans and retail accounts often carry substantially higher interest rates than prime, making additional festive borrowing particularly costly.
“We are especially concerned about the financial transition from December into January. Early salary payments, festive expenses and the return of school-related costs can create significant pressure on already stretched household budgets.
“Holding rates steady would therefore be welcome, but should not be confused with meaningful financial relief.
“Our view is that consumers need stability, particularly at a time when essential living expenses continue to absorb such a large proportion of household income. Avoiding another increase would at least prevent further deterioration in affordability,” concluded Annaline van der Poel.